BURNING CHROME | The AI bubble: When technological ambition outruns economic reality
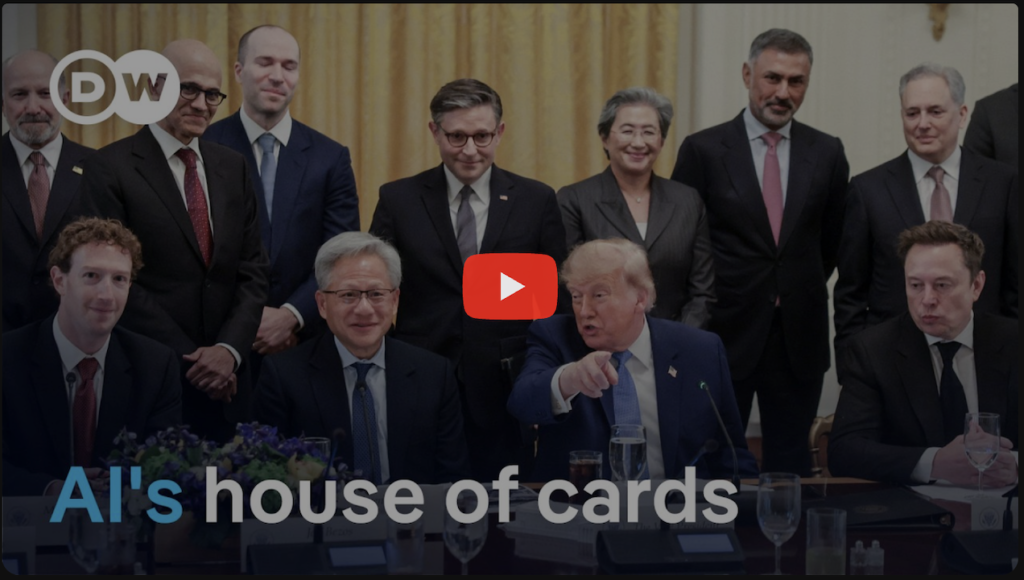
The industry’s trillion-dollar wager rests on a difficult question: Can artificial intelligence deliver enough measurable economic value to justify the capital being poured into it?
I recently came across a Deutsche Welle report on YouTube, presented by journalist Hannah Hummel, featuring Ed Zitron, an author, journalist and host of the Better Offline podcast. The report examines whether the artificial intelligence boom is built on technological promises and financial assumptions that may prove difficult to sustain. Zitron’s arguments were provocative enough to warrant a closer look.
His verdict is blunt. “This is a doomed industry,” Zitron declares, referring to the economics of the current AI boom.
It is a deliberately confrontational assessment, and his most catastrophic predictions should not be mistaken for established facts. But dismissing his argument simply because of its tone would miss the more important questions it raises about technological progress, financial speculation and the business models being built around generative AI.
The issue is not whether artificial intelligence can be useful. It demonstrably can. The issue is whether the industry’s current investment cycle, corporate valuations and promises of future growth are proportionate to what the technology can deliver and what customers are willing to pay for it.
That distinction matters because the AI industry has become remarkably good at selling the future. Its leading companies promise breakthroughs in medicine, scientific research, software development and productivity, while investors pour billions of dollars into the infrastructure required to make those promises a reality. The scale of the investment is increasingly presented as evidence that something historically significant is happening.
But capital expenditure is not proof of innovation, valuations are not proof of commercial viability, and a technology’s potential is not the same as its demonstrated economic value.
The question is whether the industry can turn its extraordinary technological ambitions into sustainable businesses, or whether the financial expectations surrounding AI have grown faster than the underlying economics can support.
The gap between capability and promise
Large language models have changed how people interact with software. They can generate text, summarize documents, assist with programming, analyze information and support a range of creative and technical tasks. In some circumstances, they can substantially reduce the time required to complete particular jobs.
But these capabilities do not automatically establish that AI systems can reliably perform complex work without human supervision.
In Hummel’s Deutsche Welle report, Zitron describes large language models as probabilistic systems that predict the next token based on patterns learned during training and subsequent refinement. Their ability to produce convincing output, he argues, should not be confused with dependable reasoning or autonomous competence.
“When it comes to large language models, they are inherently probabilistic,” Zitron says. “Just means that they are guessing the next token.”
The word “guessing” is an accessible shorthand, although it does not fully describe the mathematics, training processes or inference mechanisms behind these systems. The more consequential point is that fluent output does not guarantee factual accuracy, consistent reasoning or successful execution of a task.
A model that produces a useful piece of code is not necessarily capable of building, securing and maintaining an entire software platform. An AI system that helps researchers identify promising drug candidates has not thereby cured a disease. Each application requires its own standards of verification, testing and accountability.
These distinctions become particularly important when technology companies make claims about what their systems will eventually accomplish. The more ambitious the promise, the more important it becomes to establish what has actually been demonstrated, under what conditions and at what cost.
AI’s limitations do not make the technology worthless. They make careful evaluation essential.
The industry would benefit from a more rigorous discussion of where AI works, where it fails, how much human intervention it requires and whether its performance improves outcomes enough to justify the expense. Instead, much of the public conversation has revolved around increasingly ambitious predictions of what the technology will become.
That creates a problem when investors begin pricing the future as though it were already here.
Follow the money, not the spectacle
Zitron’s more consequential argument concerns the financial structure of the AI industry.
Developing and operating advanced AI systems requires expensive computing infrastructure, specialized chips, data centers, electricity, networking equipment and highly skilled personnel. Companies must also fund research, develop products, acquire customers and pay the ongoing cost of generating responses to user requests.
These expenses are incurred in the present. The hoped-for returns may arrive much later, if they arrive at all.
There is nothing inherently irrational about investing ahead of profitability. Many successful technology businesses spent years building infrastructure, attracting users and developing commercial markets before achieving sustainable returns. Investors may also reasonably accept losses when they believe a company is establishing a durable competitive advantage.
But those arguments do not eliminate the need to establish whether the expected returns can justify the investment.
Revenue growth is not profitability. A large customer base is not necessarily a sustainable business. And access to enormous amounts of capital does not guarantee that a company can eventually generate enough cash to support its operations.
Zitron argues that major AI developers are spending at a pace that their existing business models cannot adequately support. He also questions the extent to which revenue within the AI ecosystem reflects durable demand from customers outside the industry.
His allegation that a large proportion of OpenAI’s and Anthropic’s revenue comes from other AI startups is a specific claim that requires independent verification against company financial disclosures and reliable reporting. It should not be treated as established fact simply because it appears in an interview.
Nevertheless, the broader issue is legitimate. Investors need to know whether spending is being supported by sustainable demand, whether customers are willing to pay prices that cover the cost of delivering AI services, and whether commercial arrangements within the industry create a misleading impression of independent demand.
Consider the difference between a business that attracts customers who pay for a demonstrably useful service and one whose growth depends heavily on continuing subsidies, investor financing or commercial arrangements that ultimately rely on the same pool of capital.
Both can report impressive growth. Their long-term prospects, however, may be very different.
The challenge is to determine which model is emerging across the AI industry and which companies have the financial discipline to survive if investment becomes less readily available.
The numbers behind the narrative
One of the most useful parts of Zitron’s critique concerns annualized run rate, a metric that can make a company’s growth appear more substantial than its historical revenue alone would suggest.
A run rate takes financial performance over a shorter period and extrapolates it across a longer one, often 12 months. If a company generates $1 billion in revenue in a month, for example, multiplying that figure by 12 produces an annualized run rate of $12 billion.
The arithmetic is simple. The assumption that the same pace will continue is considerably less certain.
A strong month may reflect a temporary surge in demand, an unusually large customer contract or a short-lived market opportunity. Revenue may subsequently slow, costs may increase, or customers may leave. Conversely, a rapidly expanding company may continue to grow well beyond its current run rate.
The metric is therefore neither inherently misleading nor inherently reliable. Its usefulness depends on the context in which it is presented.
Zitron criticizes the tendency to report annualized run rates as though they were equivalent to revenue already earned over a completed year. He argues that journalists and investors should pay closer attention to the period used in the calculation and the assumptions required to sustain the resulting figure.
His criticism deserves attention because large numbers can acquire a life of their own. A company announces a projected annual revenue figure, headlines repeat it, investors interpret it as evidence of accelerating commercial success, and the resulting enthusiasm helps reinforce the valuation that made the announcement newsworthy in the first place.
The problem is not the existence of run-rate calculations. It is the failure to explain what they mean.
A responsible report should distinguish annualized run rate from recognized revenue and recurring contractual revenue, identify the measurement period and examine whether the underlying business can sustain its performance. Where available, journalists should also investigate gross margins, operating losses, cash flow, customer retention and the cost of serving additional users.
Zitron’s advice to journalists is blunt: “Stop using run rates.”
A more precise recommendation would be to stop presenting run rates without explaining their limitations.
That is not merely a technical distinction. It is a question of whether financial reporting informs readers or inadvertently amplifies the assumptions driving market enthusiasm.
Data centers and the cost of believing
The physical infrastructure supporting AI introduces another layer of risk.
Companies are investing heavily in data centers and specialized computing equipment to accommodate anticipated demand. Such infrastructure can support valuable services, but it is expensive to build, power, operate and maintain. Its financial viability depends on utilization, the cost of financing, the price customers are willing to pay and the useful life of the equipment.
Zitron questions whether the industry can sustain its infrastructure commitments if demand fails to match expectations.
In the interview, he argues that AI infrastructure is less readily reusable than the fiber-optic networks installed during the dot-com boom. The comparison deserves qualification. Data centers can support workloads beyond generative AI, and their buildings, power connections and some computing equipment may retain value even if particular AI investments fail.
Nevertheless, specialized accelerators and rapidly evolving hardware can become less competitive as newer generations arrive. Infrastructure built for one set of assumptions may also prove uneconomic if demand, utilization or energy costs develop differently than expected.
The problem is one of capacity planning. Too little computing capacity can constrain a service and frustrate customers; too much can leave operators paying for expensive resources that generate insufficient revenue.
If companies commit to infrastructure based on optimistic forecasts, a slowdown in demand could affect not only AI developers but also data center operators, equipment suppliers, cloud providers, lenders and investors.
This is where the argument moves beyond whether a particular chatbot or AI assistant is useful. The question becomes whether the financial system has taken on excessive exposure to a narrow set of technological expectations.
The Bank of England’s warnings about AI-related investment and financial stability underline the importance of this question. Concentrated market exposure, uncertain future earnings and growing financing requirements could amplify the effects of a reassessment of AI’s commercial prospects. Such warnings do not establish that a crash is imminent, but they demonstrate why the industry’s financial assumptions deserve scrutiny.
A technology can be economically significant even as some of the companies and investments associated with its development suffer substantial losses.
A bubble can burst without the technology disappearing
Zitron forecasts a market crash that could rival the dot-com collapse. He warns that many AI startups could fail, data center investments could become uneconomic and companies supplying AI hardware could face sharp declines in demand. These are predictions, not established outcomes.
A market correction is possible if investors conclude that the profits anticipated from AI will take longer to materialize, will be smaller than expected or will accrue to fewer companies than originally assumed. But the scale and timing of such a correction cannot be established from the interview alone.
The dot-com era offers a useful lesson. The collapse of internet-related valuations did not invalidate the internet. It exposed the gap between the long-term significance of a technology and the commercial prospects of businesses that had been built around it. The same distinction applies to AI.
Some companies may fail even if AI becomes a routine component of business operations. Others may survive by reducing costs, developing more effective products or finding customers willing to pay for services that demonstrably improve productivity. Established technology companies may also absorb losses on particular AI investments while continuing to benefit from the technology in other parts of their businesses.
The outcome will not necessarily be a simple choice between an AI revolution and an AI collapse. It may instead involve a prolonged adjustment in which valuations, infrastructure commitments and business models are forced to align more closely with actual demand.
The question is how much capital will be lost along the way, who will bear those losses and whether the benefits ultimately justify the expenditure.
Journalism must interrogate the claims
Zitron is particularly critical of technology journalism, arguing that reporters often repeat impressive corporate claims without examining the financial or technical assumptions behind them.
This is a familiar problem in technology reporting. Companies have an incentive to present their products in the most favorable light, while investors want to communicate confidence in their investments. Reporters face pressure to publish quickly in an environment where technical complexity and competitive secrecy can make independent verification difficult.
The result can be coverage that treats announcements as achievements, projected revenue as demonstrated commercial success and technological possibility as a prediction of inevitable adoption.
AI has intensified these tendencies because its claims extend far beyond the technology itself. A new model becomes a story about the future of work. A funding round becomes evidence of market leadership. A data center commitment becomes proof that a company is preparing for enormous demand.
Each may be newsworthy, but none establishes the broader conclusion on its own.
Journalists should ask what a model can demonstrably do, how reliably it performs, what human oversight it requires and whether the results are reproducible outside controlled demonstrations. They should examine the economics of deploying it, including the cost of computing, the price charged to customers and the measurable benefits delivered.
They should also apply the same standards to critics. Zitron’s allegations about corporate finances and his predictions of a catastrophic market correction deserve scrutiny just as corporate claims do.
Skepticism is not the automatic rejection of a company’s promises. It is the insistence that those promises be supported by evidence.
For a technology industry that regularly asks the public to believe in a future it says is inevitable, that should be a basic requirement of responsible reporting.
The Philippine question
The AI debate has implications for the Philippines, where businesses, government agencies and educational institutions are evaluating how to use AI while managing costs, security, data governance and dependence on external technology providers.
The relevant question for local organizations is not whether AI is fashionable or whether competitors are adopting it. It is whether a particular application solves a real problem, improves a measurable outcome and remains economically viable after the initial deployment.
A business should evaluate the full cost of an AI service, including subscriptions, computing requirements, integration, training, human verification, cybersecurity and maintenance. A government agency should consider whether the system improves service delivery while preserving accountability, privacy and meaningful human oversight. Educational institutions should assess whether AI supports learning rather than simply automating the production of assignments and assessments.
These decisions should be grounded in evidence of practical value rather than assumptions about the inevitable arrival of an AI-powered future.
The same principle applies to national technology policy. Investment in digital infrastructure and AI capabilities may offer substantial benefits, but public and private resources should be allocated according to credible assessments of demand, cost, resilience and long-term usefulness.
A technology’s global prominence is not a substitute for evaluating its local relevance.
Beyond the hype cycle
The strongest part of Zitron’s argument is not his prediction that the AI industry is doomed. It is his insistence that the industry’s financial claims and technological promises should not be accepted without scrutiny.
Artificial intelligence may become one of the most consequential technologies of this century. It may transform scientific research, alter software development, change the organization of work and create entirely new commercial opportunities. None of those possibilities, however, guarantees that every company developing AI will succeed or that every investment made during the current boom will generate an adequate return.
The technology’s future will be determined by more than the amount of capital attracted to it. It will depend on whether its capabilities improve, whether its costs become manageable, whether customers derive measurable value and whether the resulting businesses can sustain themselves without relying indefinitely on ever-larger rounds of financing.
The AI industry does not need to be dismissed wholesale. It needs to be evaluated without the assumption that technological progress automatically justifies financial excess.
That is also the responsibility of journalism. Reporters must distinguish between what companies promise and what they demonstrate, between revenue earned and revenue projected, and between a technology’s genuine utility and the speculative expectations surrounding its future.
In the end, the most important question is not whether AI will change the world. It is whether the companies promising to change the world can build sustainable businesses while doing so.
The answer will require less faith in the inevitability of technological progress and considerably more evidence of what that progress is actually worth.
Full disclosure: All news articles published on the TechSabado website are written by human journalists, unless otherwise specified. Final text editing is also performed by human editors, with artificial intelligence (AI) used only to assist with additional grammar and style guide corrections..
————————————————————————-
TEN YEARS OF TECHSABADO!
PLEASE LIKE our FACEBOOK PAGE and SUBSCRIBE to OUR YOUTUBE & SPOTIFY channels.
WATCH TECHSABADO ON OUR YOUTUBE CHANNEL:
WE ARE ALSO ON SPOTIFY
WATCH OUR OTHER YOUTUBE CHANNELS:
PLEASE LIKE our FACEBOOK PAGE and SUBSCRIBE to OUR YOUTUBE CHANNEL.